How Banks Can Choose the Right Banking Connect TSP and Avoid a Costly Rollout
Why Banking Connect Is a TSP Decision, Not Just a Compliance Task
India's netbanking infrastructure had a problem that persisted for years. Every payment aggregator had to build a separate, individual technical connection with every bank to process netbanking payments. With dozens of aggregators and dozens of banks, this created a complex web of one-to-one relationships. Onboarding a single merchant onto a new bank's netbanking could take 10 to 15 days.6 Dispute resolution was inconsistent. Settlement timelines varied by bank. And RBI was receiving transaction data with a lag of up to 7 days - making real-time monitoring difficult.4
"Today, banking operates as a mesh of bilateral ties between different merchants, payment aggregators and banks. Banking Connect is going to shift the heavy lifting of managing multiple banking connections from merchants and aggregators to NBBL."
Noopur Chaturvedi, MD & CEO, NBBL4- Noopur Chaturvedi, MD & CEO, NBBL4
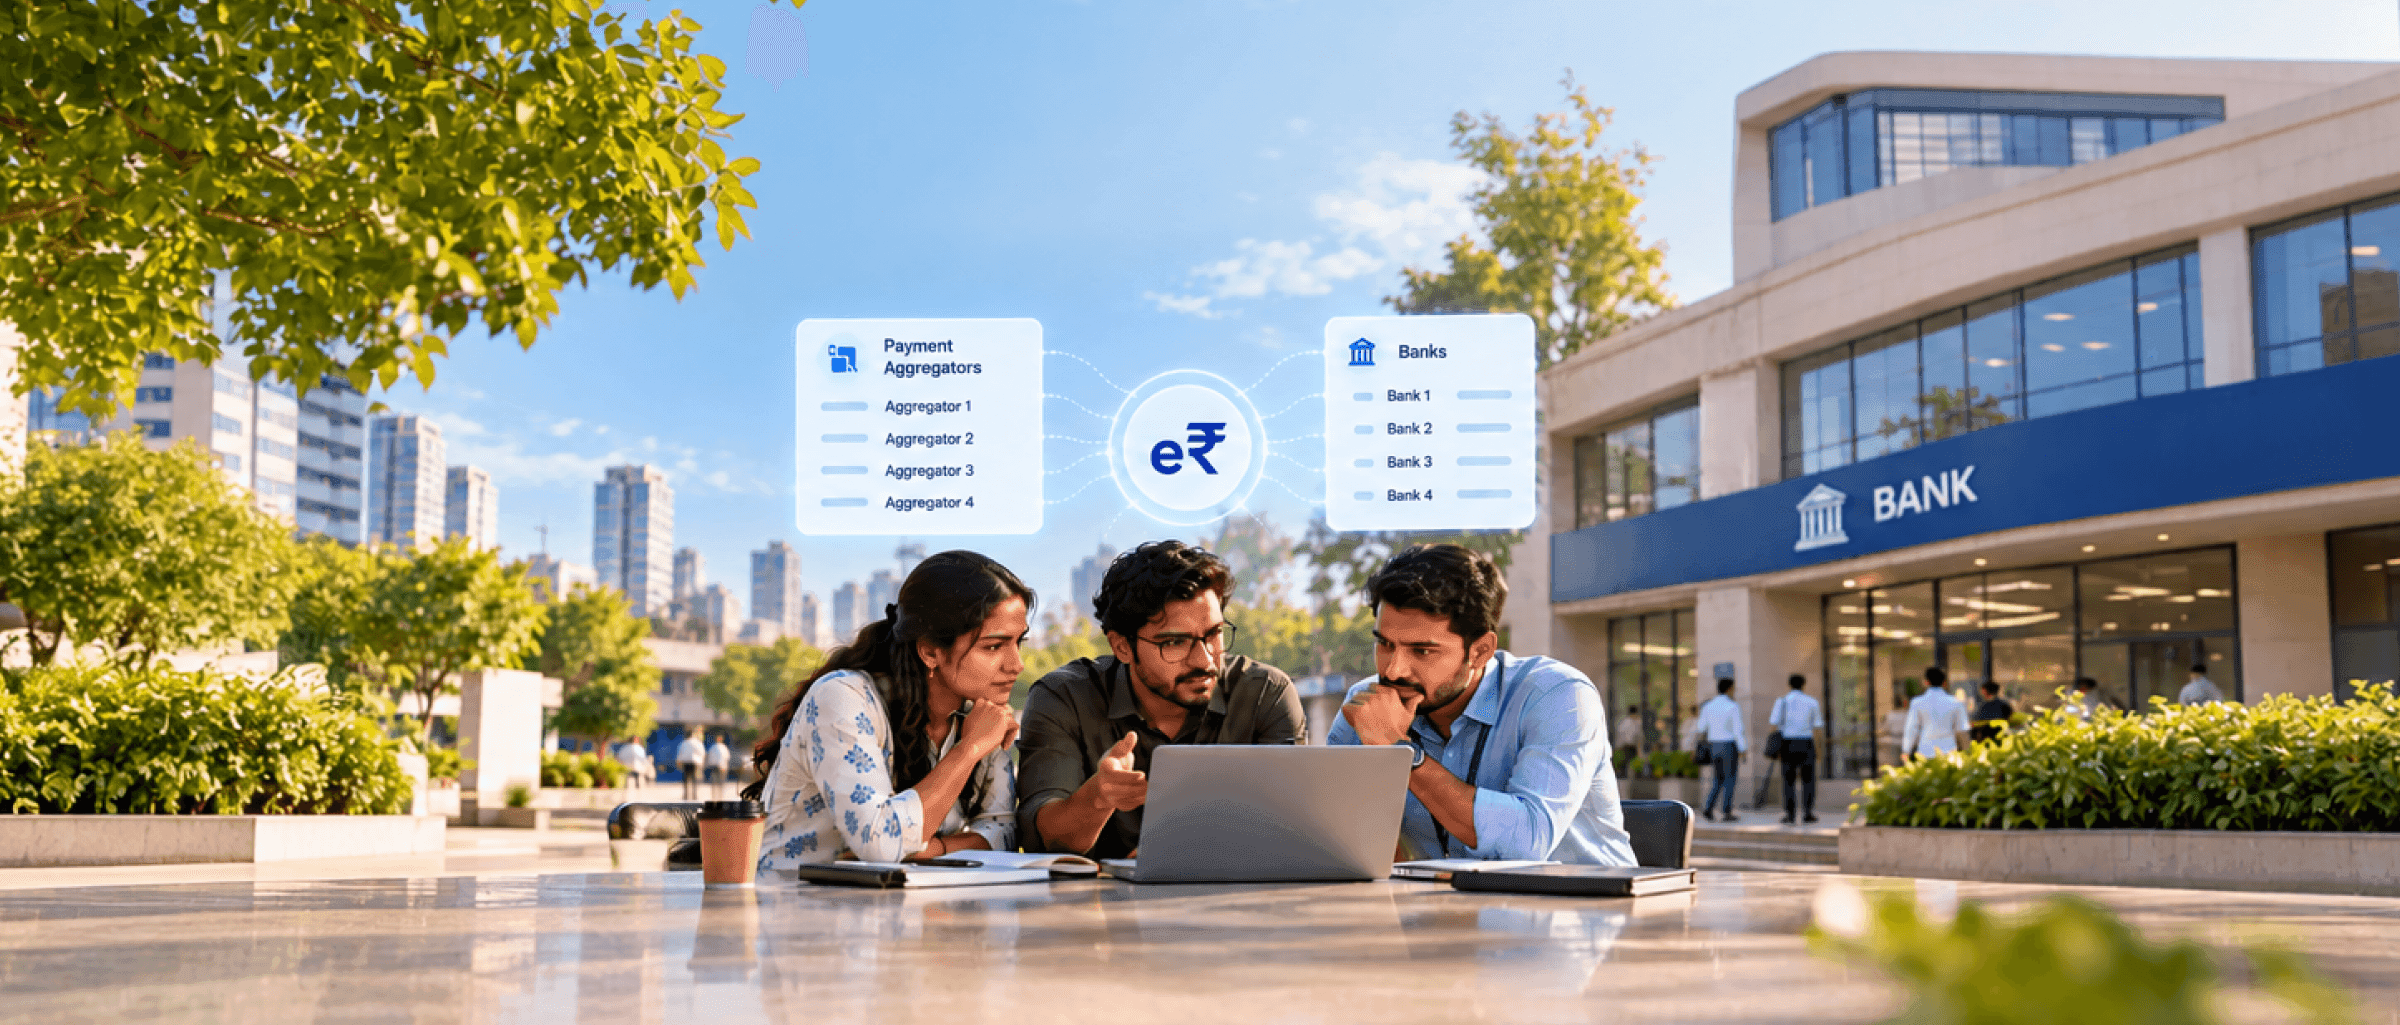
Banking Connect, developed by NBBL (NPCI Bharat BillPay Limited) and launched at Global Fintech Fest in October 2025 in the presence of RBI Governor Sanjay Malhotra, replaces that bilateral web with a single central switch.[6] The groundwork was laid in 2024, when RBI approved the implementation of interoperability for netbanking transactions specifically to address delays in merchant payment receipt.3 By April 2026, Banking Connect was live with eight major banks - SBI, ICICI Bank, HDFC Bank, YES Bank, AU Small Finance Bank, Federal Bank, and Axis Bank - and eleven payment aggregators including Razorpay, PayU, Pine Labs, Cashfree, Juspay, Zoho, and others.26 Axis Bank's integration alone connected 37 million customers to over 4,800 merchants.2
Netbanking handles over 300 million monthly transactions worth more than ₹6 lakh crore - primarily high-ticket payments where customers choose netbanking over UPI specifically because netbanking carries no per-transaction limit.1 For banks yet to go live, the decision is no longer whether to join Banking Connect because RBI's 2024 mandate has settled that. The question is which NBBL-certified technology service provider (TSP) gets the bank live fastest, with least disruption, and with enough ecosystem depth to make go-live commercially meaningful from day one.
How Banking Connect Works and Where the TSP Fits In
NBBL operates Banking Connect as a central switch. It handles clearing, settlement, dispute management, and regulatory reporting to RBI. None of this is the TSP's job. The TSP builds and maintains the technical bridge that connects a bank's existing netbanking systems to the switch without requiring the bank to rebuild its core infrastructure.
Banking Connect's platform includes:
- Standardised APIs that reduce delays, redirections, and timeout errors common in legacy netbanking flows6
- Biometric authentication support and a mobile-first design for growing mobile payment volumes6
- No transaction caps - supporting unrestricted high-value transfers6
- Real-time transaction reporting to RBI - fixing the seven-day data lag that existed in the legacy bilateral model4
A TSP's architecture should complement this design - not conflict with it. A TSP built on a monolithic stack that cannot absorb Banking Connect's API updates rapidly will create delays every time NBBL releases an enhancement. NBBL has confirmed an upcoming roadmap including Direct-to-Merchant Settlements, Third-Party Verification (TPV), and mandate and lien capabilities.2 A bank evaluating TSPs today should ask each vendor which of these roadmap features they already support and what their track record has been on implementing previous NBBL feature releases.
Criteria One: Ecosystem Depth - What Determines a Bank's reach on Banking Connect
Going live on Banking Connect and being commercially active on Banking Connect are different things. A bank can complete its technical integration with the switch and still deliver very little value if its TSP does not bring meaningful ecosystem connections to the deployment.
Ecosystem depth means proven, live connections to the payment aggregators and merchants that a bank's customers actually transact with - not a theoretical capability to integrate with them. Axis Bank's April 2026 go-live is the reference point: 37 million customers were immediately connected to over 4,800 active merchants the moment integration went live.2 That day-one reach came from NBBL's existing ecosystem of already-integrated aggregators and merchants. A bank whose TSP has deep, pre-existing relationships within that ecosystem inherits usable reach at go-live. A bank whose TSP has thin ecosystem connections goes live technically but waits months for meaningful transaction volume.
The practical questions to ask any TSP on ecosystem depth:
- How many of the eleven live payment aggregators on Banking Connect are you already integrated with?
- How many merchants can a bank's customers reach through your deployment on day one?
- Can you name the banks where your integration is live and producing actual transaction volume, not just certified?
Criteria Two: Speed to Market - Why Every Week of Delay Has a Cost
The banks that went live earliest on Banking Connect are now capturing netbanking transaction volume on a standardised, scalable infrastructure while late-joining banks are still in integration and certification. NBBL is targeting 1 billion monthly transactions across its combined bill payments, B2B, and Banking Connect products within three to four years, up from 260 million today.1 Banks that integrate early are positioned in a growing ecosystem, not joining one that has already matured.
Speed to market is determined primarily by two things: how long NBBL certification takes for the TSP and bank combination, and how much surrounding integration work the TSP has already done versus needs to be built from scratch. A TSP with prior NBBL certification experience across multiple banks has navigated the testing cycle before and it knows where the friction points are. A TSP doing its first Banking Connect certification is learning on the bank's timeline.
4 questions worth asking every TSP on deployment speed:
- What is your actual timeline from contract signing to go-live - demonstrated from a named bank deployment, not an estimate?
- Does your integration require changes to our core banking system? Verify this against a named reference, not marketing language.
- How long does merchant activation take through your platform after go-live?
- When NBBL releases a new feature update, what is your typical implementation turnaround?
The last question matters most given NBBL's confirmed roadmap. A bank that chooses a TSP with a slow feature implementation track record will face re-integration work every time NBBL releases a new capability.
Criterion Three: RBI Compliance - What Banks Are Actually Responsible For
Banking Connect's compliance framework places obligations on banks that are easy to underestimate. Most importantly, a bank is responsible for ensuring its TSP meets the same compliance standards as the bank itself. If a TSP fails a certification cycle or implements a feature incorrectly, the regulatory consequence falls on the bank and not the TSP.
3 compliance rules that must not be treated as optional:
-
Verify NBBL certification independently. Never accept a TSP's self-description of NBBL certification. NBBL maintains its own certified participant list. Any vendor's claimed status should be verified with NBBL before the bank signs a contract.
-
Settlement funds must never flow through a TSP. This is a hard requirement under NBBL's framework. The TSP's role is technology - integration, configuration, feature implementation. Money moves between banks and NBBL's settlement infrastructure directly. A TSP architecture that routes settlement funds through its own systems is non-compliant, regardless of commercial convenience.
-
The TSP's reporting architecture must support RBI's real-time visibility. Banking Connect was specifically designed to fix the seven-day transaction data lag that RBI experienced under the legacy bilateral model.4 A TSP that maintains proprietary reporting outside the NBBL framework undermines the regulatory transparency that Banking Connect was built to provide.
RBI's Payments Vision 2028, announced in March 2026, signals that the regulatory direction for digital payments is toward greater interoperability, transparency, and standardisation.7 A TSP with a demonstrated track record of adapting quickly to new NPCI and RBI requirements is materially lower compliance risk than one that lags behind.
The Revenue and Strategic Case for Moving Now
The commercial argument for Banking Connect operates on two dimensions simultaneously: it reduces costs and expands reach at the same time.
- Cost reduction: A bank currently managing bilateral integrations with multiple payment aggregators pays for each in engineering time, maintenance overhead, and incident resolution every time an aggregator updates its API or RBI issues a new compliance requirement. Banking Connect replaces all of those bilateral costs with a single integration.
- Market expansion: The bank becomes reachable to every merchant connected to any of the eleven payment aggregators on Banking Connect - and every new participant that joins the switch in the future - rather than only those merchants integrated with the bank's existing bilateral partners.
- First-mover positioning: Banks that are already live are accumulating transaction data, building operational familiarity with the platform, and establishing themselves as reliable netbanking partners for payment aggregators who are actively prioritising their Banking Connect integrations first. Later entrants will compete for aggregator bandwidth in a platform where early participants are already established.
NBBL's combined target of 1 billion monthly transactions across Bill Payments, Bharat Connect for Business, and Banking Connect within three to four years - up from 260 million today1 - represents a transaction pool that is growing. A bank integrated early captures proportionally more of that growth. Which is why the TSP a bank chooses now determines how much of that growth its netbanking channel actually captures, before the platform reaches that scale.
Why Digiledge Banking Connect Fits This Evaluation
A bank's Banking Connect outcome is determined almost entirely by its TSP. The NBBL switch itself is identical for every participant. The only variable is what the TSP brings to the deployment - ecosystem depth, deployment speed, compliance architecture, and the ability to absorb NBBL's evolving feature roadmap without requiring the bank to re-architect.
Digiledge Banking Connect is a Banking Connect SaaS platform and deployment layer built on top of the NBBL switch, not Banking Connect itself, which is NBBL's infrastructure.8 Digiledge's layer connects a bank's existing core systems to the switch without requiring changes to those core systems. The platform delivers three specific outcomes:
-** Single integration to the full ecosystem:** One connection through Digiledge's layer reaches all participating payment aggregators and merchants on Banking Connect - replacing the bilateral web with a single, maintainable integration.
-
Unified payment journeys across channels Mobile app intent flows, dynamic QR for web and multi-device scenarios, and standardised netbanking experiences - managed through one deployment layer, not separate integrations per channel.
-
Automated merchant activation and settlement Merchant onboarding via API or bulk upload, with centralised batch settlement and reconciliation - reducing the operational overhead that made legacy netbanking for merchant activation slow.
On compliance: settlement funds do not flow through Digiledge's infrastructure. NBBL certification is maintained continuously through every feature cycle - not just at initial deployment. New capabilities from NBBL's confirmed roadmap are absorbed as updates, not re-architecture.
The NBBL switch is the same for every bank on Banking Connect. What differs is everything around it - how fast the TSP gets a bank live, how much of the ecosystem it brings to day one, and how reliably it keeps the bank compliant and current as Banking Connect evolves. That is the decision a bank is actually making when it chooses a TSP. Digiledge is built to win on all three.
Digiledge, a Mintoak Company, helps banks deploy on NBBL's Banking Connect switch through a dedicated acceleration layer built for speed and ecosystem depth. If your bank is evaluating Banking Connect TSP vendors, speak to our team today.
Frequently Asked Questions
1. What is Banking Connect and how does it differ from the legacy netbanking model?
Banking Connect is a central interoperability switch developed by NBBL that connects all participating banks and payment aggregators through a single integration. In the legacy model, every payment aggregator had to build separate bilateral connections with each bank, a process that could take 10 to 15 days per merchant.6 Banking Connect replaces that with one standardised connection that provides real-time settlement, unified dispute management, and RBI oversight across all participants.
**2. What does a Banking Connect TSP vendor actually do and what are they not responsible for? ** A Banking Connect TSP vendor India builds and maintains the technical integration layer between a bank's existing core systems and the NBBL switch. The TSP handles integration, configuration, certification support, and feature implementation as NBBL releases updates. What the TSP is explicitly not permitted to do is handle settlement funds - money moves directly between the bank and NBBL's settlement infrastructure. Settlement flowing through a TSP is non-compliant under NBBL's framework.
3. What are the RBI compliance requirements banks must meet for Banking Connect integration?
For Banking Connect RBI compliance requirements, banks must ensure their TSP is independently NBBL-certified - self-certification by the vendor is not sufficient. Banks are responsible for their TSP's compliance: if a TSP fails a certification cycle, the regulatory exposure falls on the bank. Banks must also ensure their deployment supports RBI's real-time transaction visibility mandate, which Banking Connect was specifically built to address by eliminating the 7 day data lag that existed under bilateral netbanking arrangements.47
4. How does Banking Connect create a revenue opportunity for banks integrating with NBBL?
The NBBL Banking Connect revenue opportunity for banks comes from two directions simultaneously. First, eliminating multiple bilateral PA integrations reduces engineering and maintenance costs materially. Second, a bank connected to Banking Connect gains reach across all participating payment aggregators and their merchant networks - expanding the bank's accessible merchant base without requiring separate bilateral agreements. NBBL is targeting 1 billion combined monthly transactions across its platforms within three to four years, up from 260 million today.1
5. What should banks look for when choosing a Bharat Connect certified solution provider for Banking Connect?
When selecting a Bharat Connect certified solution provider for Banking Connect, banks should evaluate three criteria: ecosystem depth (how many of the eleven live payment aggregators the TSP is already integrated with, and how many merchants are reachable on day one), deployment speed (demonstrated go-live timelines from named bank deployments, not estimates), and compliance architecture (verified NBBL certification, no settlement funds flowing through the TSP, and a reporting design that supports RBI's real-time transaction visibility requirements).26
References
- 1.Business Standard - Netbanking switch to provide better visibility into transactions: NBBL CEO Noopur Chaturvedi. 260 million to 1 billion monthly transaction target, 27 November 2025. business-standard.com/industry/news/new-netbanking-switch-banking-connect-nbbl-transactions-125112701065_1.html
- 2.Business Standard - Axis Bank joins interoperable netbanking platform Banking Connect; 37 million customers, 4,800+ merchants; 8 banks and 11 PAs live; Direct-to-Merchant Settlements, TPV, mandate/lien roadmap confirmed, 9 April 2026. business-standard.com/companies/news/axis-bank-joins-interoperable-netbanking-platform-banking-connect-126040900929_1.html
- 3.Business Standard - Four banks may log in to NBBL's 'interoperable netbanking' in October, 12 September 2025. business-standard.com/industry/banking/four-banks-may-log-in-to-nbbl-s-interoperable-netbanking-in-october-125091200028_1.html
- 4.MediaNama - NPCI subsidiary NBBL rolls out platform to simplify net banking. Noopur Chaturvedi on RBI's 7-day transaction data lag and Banking Connect's real-time oversight improvement, 28 November 2025. medianama.com/2025/11/223-npci-subsidiary-nbbl-platform-net-banking-rbi/
- 5.Business Standard - Interoperability of internet banking system in 2024: RBI Governor Shaktikanta Das, 4 March 2024. business-standard.com/industry/banking/interoperable-payment-system-for-internet-banking-in-2024-rbi-governor-124030400991_1.html
- 6.Metrovaartha - NBBL's Banking Connect to Transform Internet Banking Experience. Platform features, live banks, live PAs, Noopur Chaturvedi quote, 28 November 2025. english.metrovaartha.com/economy/nbbls-banking-connect-to-transform-internet-banking-experience
- 7.NewsOnAir - RBI announces its Payments Vision 2028, 27 March 2026. newsonair.gov.in/rbi-announces-its-payments-vision-2028-outlining-roadmap-to-strengthen-expand-indias-rapidly-growing-digital-payments-ecosystem
- 8.Digiledge Banking Connect Product Page - Mintoak. digiledge.in/products/banking-connect
Share on your socials